


The financing route can matter as much as your credit score. To understand how to get approved for wheel financing, start by matching the application to the type of plan: most traditional installment lenders look for a credit score of 600 or above, while alternative options may weigh income and bank account activity. Approval criteria vary by lender.
Before committing to new tires or rims, it makes sense to understand the financing terms. Start by comparing what each option requires, what information the application asks for, and whether the payment schedule fits your budget.
This guide explains credit-based financing and no-credit-needed plans, the factors that can affect an application, and what to review before financing a vehicle upgrade. Use it to compare options and make a decision that fits your vehicle and financial priorities.
Key Takeaways
- Learn how down-payment requirements and approval amounts can differ across financing plans.
- Understand what to prepare for an application and how pre-approval can help clarify your options.
- Build a realistic budget by considering the full upgrade purchase and the repayment terms, not just the monthly payment.
- Identify the credit, income, and banking details that can influence an approval decision.
What if I need tires or rims, but have no money?
Compare the amount you may qualify for with the payment schedule before choosing a plan. A zero-down offer can lower the initial cost, but you still need to budget for every payment.
Approval Amounts and Initial Payments
Approval amounts depend on the lender’s review and the purchase amount. The limit a lender approves and any payment due upfront are separate details, so consider both before signing.
Treat the amount as an illustration, not a promised approval. If cash is tight, identify what is due upfront and what balance remains. Confirm whether payments are monthly or weekly, then check that the schedule fits your regular budget.
APR and Total Financing Cost
APR indicates the cost of borrowing, while the payment amount shows one part of the budget impact. Treat any estimate as illustrative. Add the scheduled payments to understand the total repayment, and account for any initial payment separately.
Compare that schedule with the purchase price and the stated APR. Payment plans may run 12 to 24 months, and the right frequency depends on your cash flow. For weekly budgeting, set aside part of the monthly amount regularly. Before signing, review the payment dates, APR, amount financed, and total cost together.
What are my tire and rim financing options?
Understanding how to get approved for wheel financing starts with comparing application types, not just payment plans. Some lenders offer soft-inquiry prequalification, which can indicate potential eligibility without a hard credit check. The review process and final decision depend on the program.
Online Pre-Approval Application
An online pre-approval application gathers information for an initial eligibility review. Online applications for wheel and tire financing take under five minutes to complete. Enter accurate personal, income, and banking details, then treat the result as an estimate, not a final financing agreement.
Before submitting an application, check whether it is for prequalification or a formal decision, and look for clear wording about the credit inquiry. A hard inquiry can lower a credit score by a few points. If you want an initial estimate without a hard inquiry, choose a soft-inquiry prequalification option when available.
Application and Approval Timeline
Completing an online form can take under five minutes, but the lender’s decision may take longer. Complex applications or applications requiring additional income verification may take up to 24 hours for a decision. That distinction helps set expectations when planning a purchase or comparing financing options.
Submit complete, consistent information to help avoid unnecessary follow-up. If your income details need clarification, the lender may take longer to review the application. Keep an initial estimate separate from final approval, which sets the terms you can accept.
Application Decisions and Prequalification
If you’re learning how to get approved for wheel financing, distinguish prequalification from a final decision. Prequalification can offer an early indication of potential eligibility; final approval determines the terms after review. Check whether the initial review uses a soft or hard inquiry, and read the application language before submitting it.
The Consumer Financial Protection Bureau says specialty lenders increasingly use alternative data, such as bank account activity, to assess creditworthiness. Credit history may still matter for traditional financing, while other programs may consider additional information. Compare the inquiry type, payment plan, and ownership terms before signing.
Wheel, tire, and vehicle upgrade purchases
A financing plan may cover tires, wheels, installation, or related costs only if they qualify under its terms. The agreement specifies eligible purchases and the amount financed. Deferred-interest offers and missed payments also carry risks, so review the stated consequences before accepting.
Start by defining what you plan to buy. A wheel-and-tire package, replacement tires, or a vehicle upgrade may involve different items. List the products and costs you want to finance, then compare them with the purchases and charges eligible under the plan.
Wheel and tire financing may be tied to participating retailers, which can affect the products and costs covered. Check whether the agreement covers only the wheel and tire purchase or also other approved charges. Installation may be treated separately, so don’t assume it is included in the financed amount.
Wheel and tire financing costs depend on the amount financed, APR, payment schedule, and agreement terms. A longer payment plan can increase the overall amount repaid, even if each payment seems manageable. Review total repayment alongside the monthly amount. For a vehicle upgrade, separate the core purchase from optional additions to see what drives the cost.
Review deferred-interest terms carefully. Check the promotional deadline and what happens if the balance remains unpaid. A missed payment can disrupt the schedule and lead to consequences set out in the agreement. Look for applicable charges, interest terms, and any effect on the account. Keep due dates visible and choose a payment plan that fits your regular cash flow.
Before signing, confirm the eligible purchases, identify every financed charge, and read the rules for deferred interest and late payments. This review clarifies what the plan covers and the full commitment it involves.
Approval decisions and eligibility
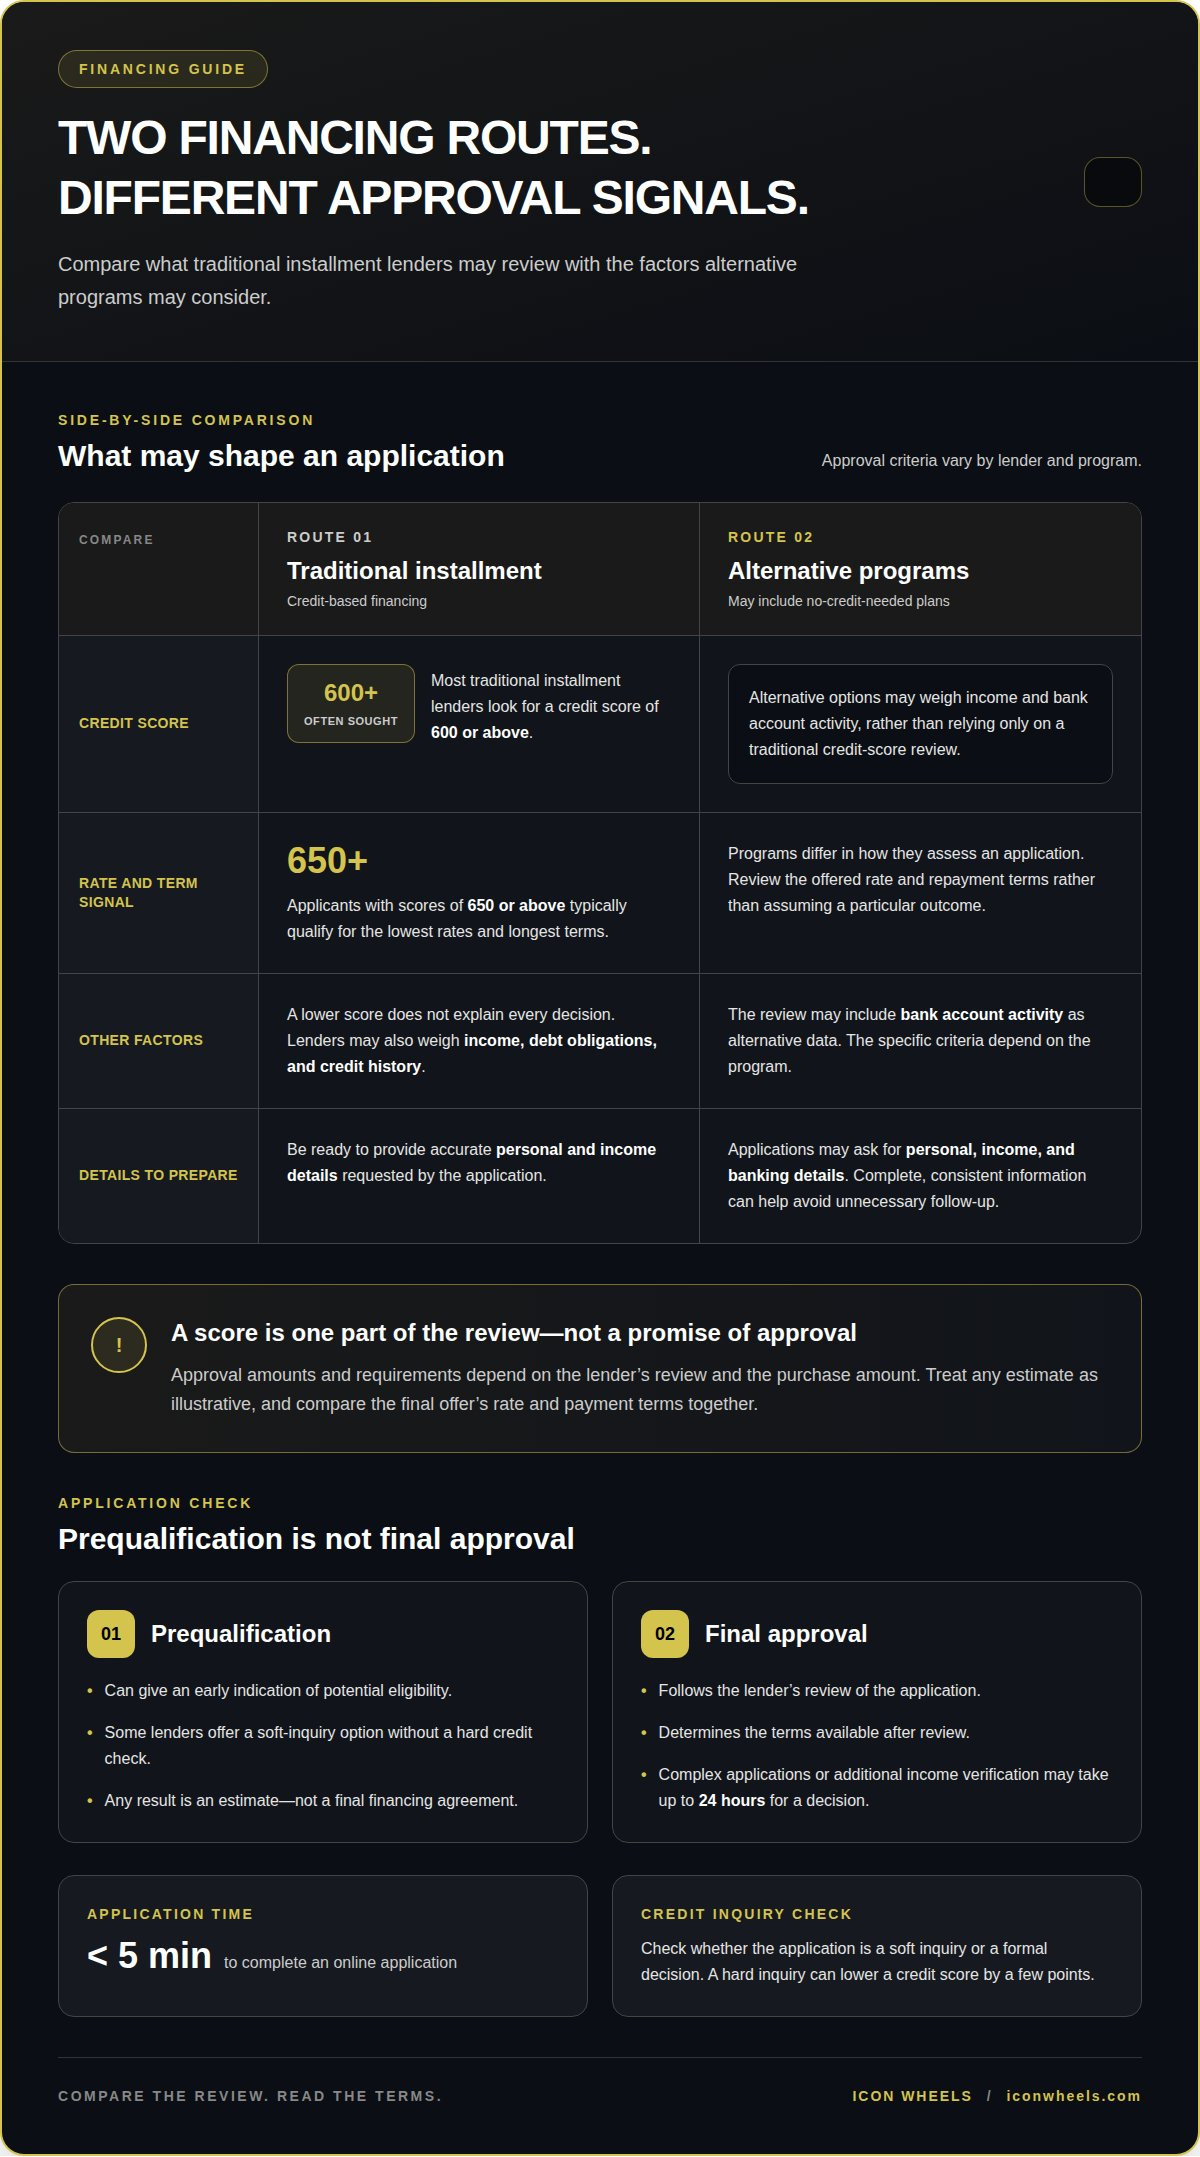
Eligibility usually depends on credit score, income, banking history, and program rules. Prepare your income details and account information, as lenders use them to assess applications and repayment capacity.
For traditional installment financing, most lenders look for a credit score of 600 or above, though requirements vary. Applicants with scores of 650 or above typically qualify for the lowest rates and longest terms. A lower score doesn’t explain every decision; lenders may also weigh income, debt obligations, and credit history. Review the offered interest rate and payment terms together.
Income can strengthen an application. Steady employment or self-employment income over the past 12 to 24 months can support standard credit-based financing. Some no-credit-needed programs require verifiable monthly income around $750 to $1,000, depending on the lender. Applicants for these plans must be at least 18 years old and U.S. residents. Requirements differ by program.
Banking details may matter, too. Many alternative wheel-financing lenders require an active checking account that has been open for at least 90 days. Gather account and income information before applying. Lenders can use these details to assess whether the requested amount and payment schedule fit your financial profile. Accurate, consistent application details make that review clearer.
Shopping for financing works best when you match the program to your situation. A stronger credit history may suit traditional installment financing, while alternative programs may assess other eligibility factors. Compare the proposed amount, interest, and repayment schedule before accepting an offer. Treat prequalification as an estimate, not a substitute for reviewing final terms.
For a tailored wheel upgrade, explore custom wheel options suited to your vehicle. Then weigh the purchase against the financing terms and your budget.
ICON WHEELS
ICON WHEELS offers a practical next step once you’re ready to choose wheels designed for your vehicle. Its offerings include Wheels For Mercedes, Wheels For Rolls Royce, Wheels For Land Rover, and Custom Built Forged Wheels. Your wheel selection defines the purchase; financing terms remain a separate part of the decision.
Turn to ICON WHEELS when you’re ready to explore wheel options for a luxury vehicle. Start with your vehicle, then narrow your selection by the style and fit you want. Defining the purchase makes it easier to review a lender’s payment plan and agreement.
Contact ICON WHEELS to discuss your vehicle and explore wheel options for your selection.
Choose Your Next Move with Confidence
Understanding how to get approved for wheel financing is only one part of a sound upgrade decision. First define the wheel style and vehicle fit you want, then assess that choice separately from the lender’s approval terms. A clear purchase goal helps you judge whether the agreement fits your plans and budget.
Look beyond the application itself. Choose wheels that suit your vehicle’s character, and assess financing terms on their own merits. This keeps the decision deliberate, from the initial selection through signing.
If you’re ready to discuss wheel options for your vehicle, contact ICON WHEELS. Move forward with a clear vision and a choice that feels right for you.
Frequently Asked Questions
How do I know I qualify for Financing?
Compare your credit profile, income, and banking history with the program’s eligibility criteria. Traditional installment lenders commonly look for a credit score of 600 or above; approval also depends on the lender’s review. Alternative programs may assess income and account activity. Before applying, identify which program you’re considering and gather accurate information about your income, checking account, and requested purchase.
How long does the financing application take?
An online wheel-financing application can take under five minutes to complete. The decision may take longer than the form itself: complex applications or cases needing additional income verification may take up to 24 hours. For example, if an application asks for more income details, allow time for that review. Keep your submitted information consistent to avoid preventable clarification requests.
What credit score do you need to get approved for wheel financing?
Most traditional installment lenders look for a credit score of 600 or above, though each lender sets its own criteria. A score of 650 or above typically qualifies buyers for the lowest rates and longest terms on traditional financing. These figures are guideposts, not automatic outcomes. Lenders may also consider income, payment obligations, and the broader credit history.
How do you apply for wheel financing step by step?
First, decide what you want to buy and how much you plan to finance. Choose a financing program and complete its application with accurate personal, income, and banking details. Check whether the initial assessment uses a soft or hard credit inquiry. Then compare the decision, APR, payment dates, and total repayment. Sign only after reading and understanding the agreement.
Can you get approved for wheel financing with bad credit or no credit?
Possibly. Alternative no-credit-needed programs may assess verifiable income and banking details rather than relying only on a credit score. Requirements can include being at least 18 years old, U.S. residency, and an active checking account. Some programs look for verifiable monthly income around $750 to $1,000. Bad-credit applicants should compare eligibility criteria and repayment terms before applying.
What are typical wheel financing interest rates, fees, and repayment terms?
Rates and fees depend on the lender, credit profile, and financing program. Financing terms may span 12 to 24 months. Review the APR, any listed fees, payment frequency, and total repayment amount together before signing.
